Treasure Coast Real Estate Blog

Aug. 11, 2026

Home Value Estimates — Agent vs Internet

Why Online Tools Miss the Mark — and What Really Determines Your Home's Value

By Eric Slifkin, Broker Associate | Keller Williams Realty Treasure Coast


You've probably typed your address into Zillow, Redfin, or one of a dozen other online estimators and watched a number pop up instantly. It feels like information — but how accurate is it, really?

The short answer: not very. And if you're planning to sell your home on the Treasure Coast, relying on that number could cost you thousands.

Home Value Estimates

What Online Estimates Actually Do

Sites like Zillow (with its "Zestimate") and Redfin use automated valuation models — algorithms that pull together publicly available data such as tax records, prior sale prices, and general neighborhood trends. They're fast, they're free, and they're useful for casual curiosity.

But here's what they can't do:

• See inside your home. That renovated kitchen, the new roof, the custom pool cage — the algorithm doesn't know they exist.

• Account for condition. A home that's been meticulously maintained versus one that's been neglected can differ by tens of thousands of dollars, even on the same street.

• Measure real-time buyer demand. Is there a bidding war happening right now in your neighborhood? Are out-of-state buyers flooding Martin County this month? No algorithm tracks that in real time.

• Understand your layout and lot. A corner lot, a water view, a dead-end street — these details move the needle significantly, and no database captures them accurately.

• Reflect off-market activity. Many Treasure Coast transactions, especially in the luxury segment, happen off-MLS. That data never makes it into the algorithm.

Zillow itself has acknowledged that its Zestimate carries a median error rate of roughly 2–3% for on-market homes — and significantly higher for off-market properties. On a $650,000 Martin County home, a 3% error is nearly $20,000 in either direction.


What a Local Agent Does Differently

A Comparative Market Analysis (CMA) from an experienced Treasure Coast agent isn't just a number — it's a judgment call backed by real data and local knowledge.

Here's what goes into a professional home valuation:

Recent comparable sales — Not just any sales, but the right ones. Similar square footage, lot size, and finishes; sold within the last 90 days. In a market as varied as Martin County — where a waterfront home in Sewalls Point and a golf course villa in Mariner Sands are both technically "Stuart" — choosing the right comps is an art.

Active listing competition — What are buyers looking at right now? If three similar homes are sitting on the market at $675K, pricing yours at $699K requires a compelling reason. Your agent knows what's out there.

Market velocity — Are homes selling in 30 days or 90? Are sellers getting full asking price or accepting concessions? In June 2026, Martin County single-family homes were going under contract in a median of 48 days — down from 56 days a year ago. That's a meaningful shift that affects how you price and when you list.

Buyer demand trends — Cash buyers represented 46% of Martin County closings in June 2026. That tells you something about who's shopping and what they value. A local agent reads those signals and prices accordingly.

Your home's specific features — Impact windows, a whole-house generator, an updated primary suite, a three-car garage. These add real value that no automated tool can quantify.


The Cost of Getting It Wrong

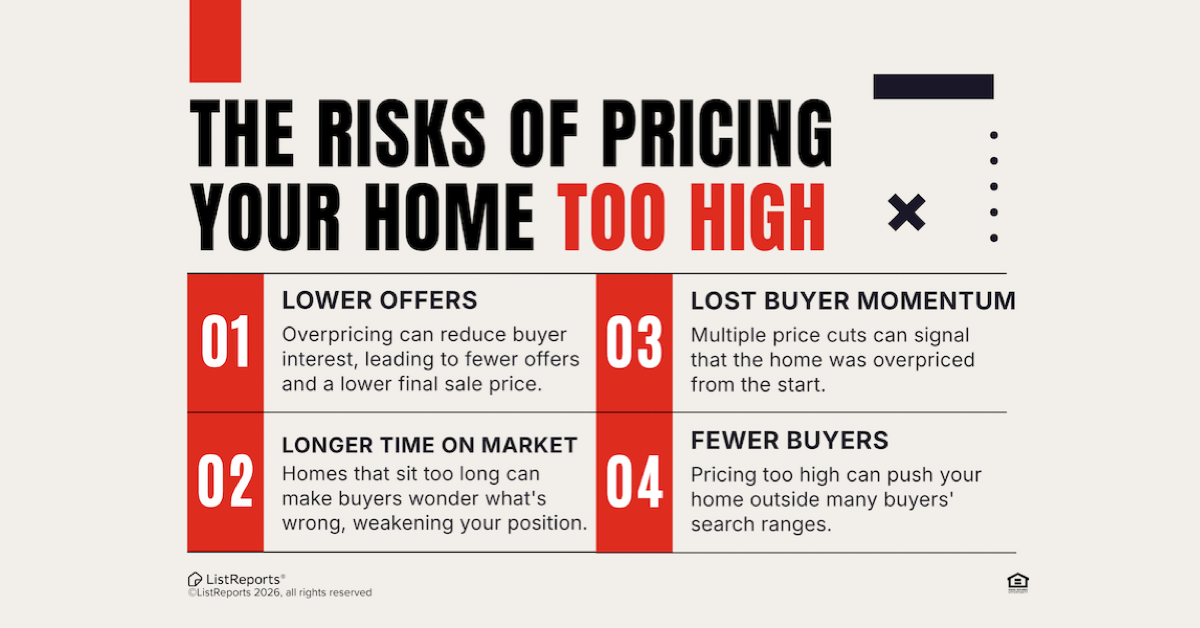
Overpricing your home is the most common and costly mistake sellers make. A home that sits on the market too long develops a stigma — buyers wonder what's wrong with it. Price reductions signal weakness and often result in a final sale price lower than it would have been if the home had been priced correctly from day one.

Underpricing is less common but equally damaging. Leaving $20,000, $30,000, or more on the table because you trusted an algorithm over a professional is a real risk in a market where inventory compression is working in sellers' favor.

The right price — informed by a skilled agent's analysis — is the one that attracts qualified buyers quickly, generates competitive interest, and closes at or near full value.

What's Your Treasure Coast Home Actually Worth?

If you're curious about your home's value — whether you're thinking about selling now or want to know where you stand — we'd be happy to put together a no-obligation Comparative Market Analysis for your specific property.

We serve Stuart, Palm City, Jensen Beach, Hobe Sound, Hutchinson Island, Sewall's Point, Tequesta, and communities throughout Martin and St. Lucie Counties.


Get Your Free Home Valuation →

Or call Eric Slifkin directly: 772-288-1765
The Slifkin Real Estate Team at Keller Williams Treasure Coast


Aug. 5, 2026

Should You Sell or Rent Your Home? What Your Low Mortgage Rate Means Right Now

If you bought or refinanced your home between 2019 and 2021, there's a good chance you're sitting on a mortgage rate most buyers today would love to have. That's a great position to be in — until you need to move. Right now, nearly half of all homeowners have a mortgage rate of 4% or lower, and almost 8 in 10 have a rate below 6%. The average rate on a new 30-year mortgage, meanwhile, is sitting at 6.58%. That gap is why so many homeowners are asking the same question: should I sell my house or rent it out instead?

Are you an accidental landlord?

Image Source: The Close

Why your low rate makes selling feel expensive

Here's the tradeoff nobody loves to think about: when you sell your current home, you also give up your current mortgage. If you buy another home, you'll likely finance it at today's rate — which could be two points or more above what you're paying now. On a similarly priced home, that difference can add hundreds of dollars to your monthly payment.

Research on this exact situation found that for every one-point gap between your original rate and today's rate, you become roughly 18% less likely to sell. It's not that homeowners don't want to move — it's that moving now costs more than it used to.

Of course, life doesn't always wait for interest rates to drop. A new job, a growing family, a divorce, or a relocation can make moving necessary regardless of the math. That's exactly why more owners in your position are choosing a third option: renting out their current home instead of selling it.

Why more homeowners are renting instead of selling

You're not alone if this feels like new territory. A recent analysis of rental listings found that 2.3% of homes currently for rent had been listed for sale within the past few months — the second-highest share recorded in nearly six years. In plain terms: a growing number of people who tried to sell their home ended up renting it out instead, often without ever planning to become a landlord.

This shift shows up most in places where homes are taking longer to sell, and buyers have more negotiating power — markets like Denver, Houston, Austin, and San Antonio. Single-family homes are especially likely to become rentals, more so than townhomes or condos, because they tend to attract stronger rental demand.

If your home didn't sell — or you're hesitant to list it because of what you'd give up — renting might be worth a serious look. But it's not automatically the right move for everyone.

What is an "accidental landlord"? An accidental landlord is a homeowner who ends up renting out their property without ever planning to be in the rental business — usually because selling stopped making financial sense. If that sounds like where you're headed, read our full guide: Becoming an Accidental Landlord →

What renting your home actually costs.

Before you decide to keep your house and rent it out, it helps to know that renting isn't free money on top of your mortgage. Your rental income needs to cover realistically:

  • Your mortgage principal and interest
  • Property taxes and homeowners insurance
  • HOA dues, if applicable
  • Vacancy periods between tenants
  • Repairs and maintenance
  • Property management fees, if you hire help

If you have significant equity and a low payment, you likely have more flexibility to rent profitably or to hold out for the right offer. If your margins are tight, renting could end up costing you more than a price adjustment would have.

How to decide: sell or rent?

The clearest way to answer this question is to compare your options side by side rather than guessing. Before you decide, it's worth gathering:

  1. What your home could realistically sell for, based on recent comparable sales in your area.
  2. What your home could realistically rent for, based on current listings nearby.
  3. Your full costs as a landlord — mortgage, taxes, insurance, HOA, maintenance reserves, and management, if you don't plan to self-manage.
  4. How long you'd actually need or want to rent the home, and what your plan is after that.
  5. Your reserves — enough to cover a vacancy, a major repair, or a slow rental season without financial strain.

Once you can see your likely sale proceeds next to your likely rental cash flow, the right decision usually becomes much clearer. And because taxes, insurance, legal requirements, and day-to-day property management each come with their own rules, it's worth looping in a CPA, an insurance agent, an attorney, and a property manager before you commit either way.

The bottom line

Your mortgage rate isn't just a number from your closing paperwork — right now, it's one of the biggest factors in whether selling or renting makes more financial sense. Neither option is automatically better. But running the numbers before you decide can save you from a costly surprise, whether that's an underpriced sale or an unprofitable rental.

If you're weighing whether to sell or rent your home, we can walk you through both scenarios and help you see the real numbers before you decide. Reach out to schedule a consultation.


Source: The Close

July 17, 2026

The 21st Century ROAD to Housing Act Is Now Law: What It Means for Treasure Coast Buyers and Sellers

The 21st Century ROAD to Housing Act — the most significant federal housing legislation in decades — is officially law. It became effective on July 11, 2026, after President Trump let the 10-day review window lapse without signing or vetoing it, an unusual path to enactment that followed a bipartisan 358-32 vote in the House and an 85-5 vote in the Senate in late June.

Road to Housing Act

Here's what's actually in it, and what it does (and doesn't) mean if you're buying or selling on the Treasure Coast.

Why This Law Exists

The backdrop is a real affordability squeeze. The median price of an existing home nationally hit $440,600 in June 2026 — up 49.2% from June 2020 — while 30-year mortgage rates are still hovering above 6.5%. Realtor.com estimates the U.S. is short roughly 4 million homes relative to demand. The Act is a bipartisan attempt to chip away at that gap by targeting the regulatory and financing bottlenecks that slow new construction.

The Provisions That Matter Most

Limits on large institutional investors. Investors who already own at least 350 single-family homes are now barred from purchasing additional single-family homes, with exceptions carved out for certain build-to-rent and renovate-to-rent projects and programs that help renters build credit toward eventual homeownership. The intent is to curb corporate competition for existing housing stock, particularly in Sun Belt markets where institutional buying has drawn scrutiny — though economists note investor activity is relatively light in many of these markets to begin with.

Zoning and permitting reform. The law streamlines environmental review requirements under the National Environmental Policy Act (NEPA) for housing projects, expands categorical exclusions, and creates competitive grants to help local governments modernize zoning and land-use rules. It also allows HUD to delegate certain reviews to states and localities — aimed at reducing the time and cost of getting new housing approved and built.

A broader definition of "manufactured home." The law updates the federal definition to include factory-built homes that are not constructed on a permanent steel chassis. Removing that requirement could lower the cost of a manufactured home by an estimated $5,000–$10,000, according to the Niskanen Center, making it a more viable entry point to homeownership.

A small-dollar mortgage pilot. A new four-year pilot program aims to expand access to mortgages under $100,000 — loans many lenders currently avoid due to compliance costs — by subsidizing lenders to originate them and offering borrowers grants for down payments and closing costs. This could matter most in lower-cost pockets of the market.

What This Means Locally

For Treasure Coast buyers and sellers, the honest answer is: don't expect overnight change. As Cotality chief economist Selma Hepp put it, "housing development takes time and many of the benefits would likely materialize gradually rather than overnight." Zoning and permitting are still fundamentally local decisions — Martin, St. Lucie, and surrounding county and municipal rules will determine how much of this translates into new supply here, and on what timeline.

That said, a few things are worth watching:

If institutional buyers pull back on single-family acquisitions, that could modestly ease competition for move-in-ready homes in the price ranges those investors have favored.

Local zoning grant funding could eventually support more housing variety in our area, though any impact will lag well behind the law's effective date.

Buyers priced out of conventional financing may want to keep an eye on the small-mortgage pilot program as it rolls out — it could open doors for lower-cost purchases, including some manufactured and 55+ community housing.

Bottom Line

This is a real, structurally significant piece of legislation — the biggest housing bill since 1990 — but it's a long-term supply and financing fix, not a quick fix for today's prices or rates. If you're weighing a move in this market, the fundamentals that matter right now are still local: pricing strategy, timing, and understanding your specific market segment. That's where I can help. Questions about your home-buying or selling plans? Let's talk.

Sources:

Eric Slifkin, Broker Associate

Keller Williams Realty Treasure Coast

O: 772-678-1600 · C: 772-288-1765

Get in Touch


July 14, 2026

Selling Your Home? Here's What You Need to Know About Your Marketing Options

If you're thinking about selling your home, you've probably assumed there's only one way to do it: put it on the market, list it on the MLS, and let the world see it. In most cases, that's exactly the right move. But it's not the only option — and as your agent, it's my job to make sure you know all of them before we decide together how to market your home.

Marketing Plan to Get Your Home Sold for Top Dollar

Here's a breakdown of the three main paths sellers can take, and why you might choose one over another.

Option 1: Full MLS Marketing (the right call for most sellers)

This is the traditional, tried-and-true approach, and it's still the best choice for the vast majority of sellers. Your home gets listed on the MLS and is broadly exposed to every agent and buyer in the market — not just those working with my brokerage.

Why it works: more eyes on your listing mean more competition, and more competition typically means stronger offers. You also get full transparency, accurate pricing history, and immediate syndication to the major real estate websites that buyers scroll through every day. Fair housing and equal opportunity protections are baked into the process, too.

If your goal is to sell for the most money in the least time, this is almost always the way to go.

Option 2: Office Exclusive Listing (for sellers who need privacy)

Sometimes maximum exposure isn't the priority — privacy is. An office exclusive listing is filed with the MLS but is not publicly marketed or advertised. It's shared only with agents inside my own brokerage, meaning it never hits the open market.

This option tends to make sense for sellers dealing with unique circumstances: a high-profile situation where discretion matters, personal or family circumstances you'd rather keep private, or simply wanting to quietly test the waters before committing to a full public launch.

The tradeoff is real: you're giving up the broad exposure and buyer competition that come with full MLS marketing. That's why I'll always walk you through exactly what you're gaining and giving up before you choose this route — it should be an informed decision, not a default one.

Option 3: Coming Soon / Delayed Marketing (the best of both worlds)

This is the strategic middle ground. A "Coming Soon" or delayed marketing listing lets us build early buzz and generate buyer interest before your home officially hits the public market.

It also buys us something valuable: time. Time to finish staging, nail the photography, and get every detail right — without the pressure of a live listing already sitting on the market. Your home stays on the market and MLS-visible throughout, just on a timeline that works for you instead of racing to post on day one.

For sellers who want a strong launch without sacrificing prep time, this option often strikes the right balance.

So, Which Option Is Right for You?

There's no universal answer — it depends on your goals, your timeline, and your circumstances. Maybe maximum exposure and the strongest possible offer is exactly what you want. Maybe privacy matters more to you right now. Maybe you just need a few extra weeks to get your home market-ready without the clock already running.

Whatever the case, my job is to explain each option clearly, make sure you understand the trade-offs, and support whichever path best serves your interests — because that's the whole point.

Thinking about selling? Let's talk through your options.

Posted in Home Selling
July 12, 2026

Treasure Coast Housing Market

TCPalm's Housing Market 2026

Curated articles about the changing real estate market on Florida's Treasure Coast. [Source: Jack Randall, TCPalm.com]

Treasure Coast Living

Home Prices Rise in all but 1 Treasure Coast County as Inventory Drops

Treasure Coast home prices are rising as inventory tightens, creating a competitive market for local buyers. Home prices are rising as inventory falls on the Treasure Coast. Median sale prices for Martin and Indian River counties increased in May compared to May 2025. The median sale price in St. Lucie County was unchanged compared to last year. The stability has been reassuring, as St. Lucie County shows several signs of "economic strain and mortgage distress," according to a report by real estate data company ATTOM. The county had a foreclosure rate higher than 90% of all U.S. counties. The number of homes sold fell in St. Lucie and Indian River counties, while rising in Martin County, compared to last year. The number of homes on the market decreased in all three Treasure Coast counties. [Source: TCPalm, 6.25.26]  Read More


Florida Home Mortgages Denied at a High Rate in St. Lucie County

Prospective homebuyers in St. Lucie County have both purchased home loans and been denied mortgages at the highest rates on the Treasure Coast and South Florida, according to a TCPalm analysis of federal data. St. Lucie County had the second-highest rate of mortgage purchases in 2024 among Florida counties, according to the TCPalm analysis. However, it also had a high rate of denials, shutting many families out of homeownership. [Source: TCPalm, 4.07.26]


Population Growth Slows on the Treasure Coast

Population growth in Port St. Lucie, once the fifth-fastest-growing metropolitan area in the nation, slowed during 2024-2025, according to a recent U.S. Census report, dropping the city to the 14th-fastest-growing metro area. The Port St. Lucie metro area, which includes Martin and St. Lucie counties, grew by 2.14% last year, according to U.S. Census data. It's the lowest annual percent growth since the post-pandemic population boom, which has averaged 3%. [Source: TCPalm, 3.31.26]


Real Estate Market Dips Again for Condos and Townhomes in St. Lucie County

The median sale price for townhouses and condominiums in St. Lucie County dropped by $75,000 from last year. In contrast, median sale prices for other Treasure Coast counties remained mostly steady in February. Last month, St. Lucie County had a median sale price of $250,500 for townhouses and condos, 23% less than in February 2025, according to a TCPalm analysis of Realtor data. [Source: TCPalm, 3.25.26]


Florida Real Estate Market Sees Home Prices Plummet in Martin County

The median price of homes in Martin County was about $100,000 less than last year's median sale price. In contrast, median sale prices for other Treasure Coast counties remained mostly steady in February, and the number of homes on the market dropped in all three Treasure Coast counties compared to last year. [Source: TCPalm, 3.24.26]


Florida Local Condo, Townhome Prices Drop

The townhouse and condominium market on the Treasure Coast is going through notable changes, with median sale prices falling and inventory increasing in some areas. The median sale price for townhouses and condos in Indian River County dropped to $185,250 in January, the lowest in years, based on data from local Realtors. The county also recorded the highest number of new listings in a single month. Martin, St. Lucie, and Indian River counties all began the year with a slowdown, according to Realtor data. "The condo and townhome market is clearly adjusting, with higher inventory and softer prices creating short-term pressure," Robenson Juste, president of the Realtors Association of Indian River County, said in a statement. [Source: TCPalm, 2.26.26]


Local Real Estate Market Flooded with Home Listings in January

January experienced the largest single-month increase in new home listings in years, according to local Realtor data. The first month of the year is typically the most popular time to list homes on the Treasure Coast market. Notably, last month saw 1,905 new listings, according to Realtor data, which is 22% more than in January 2025. However, the median home sale price in Martin County dropped by nearly $100,000 from last year, according to local Realtor data. In contrast, median home sale prices in St. Lucie and Indian River counties increased during the same period.[Source: TCPalm, 2.25.26]


Are you looking to buy or sell a Treasure Coast home? Partner with our experienced agents in Stuart, Florida, to navigate the housing market shift. Looking to sell? Maximize your property's visibility to attract more potential buyers and achieve your real estate goals. Contact us today!


Posted in Market Reports, News
June 29, 2026

The Risks of Pricing Your Home Too High

When you decide to sell your home, it's tempting to set a high asking price. Maybe you've seen what a neighbor got last year, or Zillow's Zestimate is flattering, or you just want room to negotiate. It's a natural instinct — but it's one of the most expensive mistakes a seller can make. Here on the Treasure Coast, we see it regularly: a well-maintained home sits on the market for 60, 90, even 120 days while comparable homes sell in weeks. Almost always, the culprit is the same — it was priced too high from the start. Here are five very real risks of overpricing your home, and why the right price from day one is almost always the better strategy.

Treasure Coast home seller reviewing listing price strategy with real estate agent

1. You Miss the Most Important Window — the First Two Weeks

The moment your home is listed, it gets a surge of attention from buyers who've been actively searching and have alerts set up. This is your hottest audience: motivated, pre-qualified, and ready to act. If your price is out of step with the market, those buyers scroll right past you — and go under contract on a home that is priced right.

Once that initial window closes, you're relying on new buyers entering the market. That's a much smaller pool, and you've already lost momentum.

2. Buyers Assume Something Is Wrong

There's a reason experienced buyers and their agents look carefully at "days on market." When a home sits, the assumption isn't "great, we have time to think about it." It's "what's wrong with it?"

Buyers begin to wonder if there's a hidden inspection issue, a title problem, a difficult seller, or structural concerns the photos don't show. The longer a home sits, the harder it becomes to overcome that perception — even if the home is perfectly fine.

3. You'll Likely Net Less Than If You'd Priced It Right

This is the counterintuitive part that surprises many sellers: overpricing often results in a lower final sale price than strategic pricing would have produced.

When you finally reduce the price (and most sellers do), you've already burned through the best buyers. The offers that do come in tend to be lower and more aggressive because buyers factor in that the property has been sitting. Studies consistently show that homes that sell in the first few weeks typically sell closer to — or above — list price, while homes that linger tend to sell significantly below it.

4. Appraisal Problems Can Kill the Deal

Even if an enthusiastic buyer agrees to your price, the deal isn't done. Their lender will order an appraisal — and the appraiser doesn't care what you're asking. They care about what comparable homes have actually sold for.

If your home doesn't appraise at the contract price, the buyer either has to come up with the difference in cash, you have to lower the price, or the deal falls apart. None of those are good outcomes.

5. You're Helping Your Competition

Here's something sellers rarely consider: an overpriced listing actually makes competing homes look better. Buyers who tour your home and find it overpriced don't stop shopping — they go make an offer on the comparable property that's priced correctly.

Your listing, in effect, is driving traffic to your neighbors.

What Smart Pricing Actually Looks Like

Strategic pricing isn't about pricing low. It's about pricing accurately — at the point where market data, current absorption rates, and buyer demand converge. An experienced agent will pull a comparative market analysis (CMA) looking at recent closed sales, active competition, and pending listings to find that sweet spot.

On the Treasure Coast, market conditions can vary significantly between Stuart, Palm City, Jensen Beach, Port St. Lucie, and even neighborhood to neighborhood. A home in Sailfish Point competes against a very different buyer pool than one in Palm City or Hutchinson Island. Local expertise matters.

When a home is priced right, it attracts multiple interested buyers, creates urgency, and often results in stronger offers — sometimes above list price. That's the outcome most sellers actually want.

The Bottom Line

Pricing your home is part art, part science, and entirely consequential. The good news is you don't have to guess. An experienced Treasure Coast listing agent will give you a clear, data-backed pricing recommendation — and explain exactly why it positions you for the best possible outcome.

Curious what your home is worth in today's market? Contact Eric Slifkin for a personalized market analysis and honest pricing consultation.


June 21, 2026

First-Time Homebuyer Tips: What to Know Before You Buy on the Treasure Coast

"Don't wait to buy real estate. Buy real estate and wait." -Will Rogers

Many first-time homebuyers delay their purchase, waiting for "perfect" market conditions. But interest rates and home prices are impossible to time perfectly, and waiting too long can mean missing out on the right home at the right price.

If you're considering buying your first home, focus on your finances, your long-term goals, and what you can realistically afford. A trusted Treasure Coast real estate agent can help you weigh your options and decide if now is the right time to buy.

First Homebuyer Tips

Key Considerations for First-Time Homebuyers

Browsing listings is exciting, but letting that excitement drive your decisions can lead to costly mistakes down the road. Here's how to buy your first home the smart way.

1. Choose a Reputable Real Estate Agent

Buying your first home is one of the biggest financial decisions you'll make, so work with an agent you trust. You don't need the most experienced agent in town — some buyers prefer a motivated up-and-comer — but choose someone who communicates clearly and knows the Treasure Coast neighborhoods you're interested in.

2. Get Your Finances in Order

Having savings doesn't automatically mean you qualify for a mortgage. Meet with a financial advisor to get a clear picture of what you can truly afford. If you're calculating it yourself, list every expense — loans, student debt, monthly bills — rather than relying on your lender's estimate alone. Lenders look at your debt-to-income ratio, not your everyday spending habits.

3. Get Pre-Qualified, Then Pre-Approved

Once you know your budget, confirm it with a lender by getting pre-qualified for a mortgage. Pre-qualification isn't a guarantee of funding, but it factors in your credit score and income to estimate what a lender might offer. The next step is a mortgage pre-approval letter, which proves to sellers that you can secure financing when you find the right home.

4. Shop Around for Lenders

Mortgage rates have generally been improving, but don't accept the first offer you get. Compare multiple lenders to find the best rate and terms. Mention that you're a first-time homebuyer — it may open the door to additional loan programs and benefits.

5. Explore First-Time Homebuyer Programs

Many programs exist specifically to help first-time homebuyers, offering down payment assistance, reduced closing costs, or below-market interest rates. Research what's available in Florida and on the Treasure Coast so you don't leave money on the table.

FAQ

How much do I need for a down payment on my first home?

It depends on the loan program. Conventional loans often require 5–20%, while FHA loans can go as low as 3.5%, and some first-time homebuyer programs offer down payment assistance that lowers this even further.

What's the difference between pre-qualification and pre-approval?

Pre-qualification is an informal estimate of what you might be able to borrow. Pre-approval is a more thorough review of your credit, income, and finances, and results in a letter you can show sellers to prove you're a serious, financed buyer.

What first-time homebuyer programs are available in Florida?

Florida offers several programs through Florida Housing and local county initiatives that provide down payment assistance, closing cost help, and competitive interest rates for qualifying first-time buyers. A lender or agent can help you check eligibility.

Do I need a real estate agent to buy my first home?

You're not required to have one, but a knowledgeable agent helps you navigate contracts, negotiations, and local market conditions, often at no direct cost to you since the seller typically covers agent commissions.

What costs should I budget for besides the down payment?

Plan for closing costs (typically 2–5% of the purchase price), home inspection fees, appraisal fees, and moving expenses, along with an emergency fund for repairs after move-in.

Ready to Buy Your First Home on the Treasure Coast?

Navigating the real estate market can feel overwhelming, but a solid strategy makes all the difference. Eric Slifkin and his team of licensed Treasure Coast real estate professionals specialize in guiding first-time homebuyers through every step of the process — from financing to closing. Ready to find your dream home? Let's connect.

June 14, 2026

The Role of a Listing Agent

The Slifkin Team at Keller Williams Realty

Listing Agents in Stuart, Florida, and the Treasure Coast

Choosing the right real estate team is essential if you're ready to sell your home. Eric Slifkin and his team of licensed real estate professionals offer reliable, professional service to help you through the process. We are well-versed in the local market and are committed to selling your home quickly and at the best possible price.

The Role of a Listing Agent

What Does a Listing Agent Do?

Pricing Your Home Right

A skilled listing agent starts with a comparative market analysis (CMA) and current local data to price your home competitively from day one. Getting the price right from the start helps you avoid the "overpriced and stale" trap, where a home sits on the market too long and buyers start to wonder what's wrong with it.

Marketing That Gets Results

Once your home is priced right, it becomes the focus of a daily marketing effort through our 100+ Point Marketing Plan — including professional photography and video, targeted social media and email campaigns, paid advertising on Google, Zillow, and Realtor.com, optional Matterport 3D tours, and printed materials for buyers and agents touring in person.

Negotiating on Your Behalf

When offers come in, your listing agent negotiates price, terms, escalation clauses, and repair requests on your behalf — working to protect your bottom line whether you receive one offer or several at once.

Managing Paperwork and Deadlines

From disclosures to inspection contingencies, appraisals, and title work, your agent tracks every deadline in the contract so nothing falls through the cracks between acceptance and closing.

Guiding You to Closing

Your listing agent coordinates with lenders, attorneys, and title companies, and walks you through the final walkthrough — staying with you every step of the way to the closing table.

Learn More About Selling a Home on Florida's Treasure Coast →

Frequently Asked Questions

How much does a listing agent cost?

Listing agent commissions are negotiable and are typically paid by the seller at closing as a percentage of the final sale price. The exact rate depends on the services provided, the local market, and what's agreed to in your listing agreement. Eric Slifkin and The Slifkin Team are happy to walk you through exactly what's included in your marketing plan so you know what you're getting for the commission you pay.

What's the difference between a listing agent and a buyer's agent?

A listing agent represents the seller and is responsible for pricing the home, marketing it, negotiating offers, and guiding the seller through closing. A buyer's agent represents the buyer, helping them find homes, submit offers, and navigate the purchase process. Some agents represent both sides on different transactions, but on any single sale each side typically has its own dedicated representative.

Do I need a listing agent to sell my home?

You're not legally required to use a listing agent, but selling on your own means handling pricing strategy, marketing, showings, negotiations, disclosures, and closing paperwork yourself. A listing agent brings local market knowledge, a built-in marketing plan, and experienced negotiation to help you sell faster and for a stronger price — often more than offsetting the cost of representation.

What does a listing agent do to market my home?

A strong listing agent does far more than place a sign in the yard. The Slifkin Team's 100+ Point Marketing Plan includes professional photography and video, targeted social media and email campaigns, paid advertising on Google, Zillow, and Realtor.com, optional Matterport 3D tours, and printed materials for buyers and agents touring in person — all designed to put your home in front of serious, qualified buyers every day it's on the market.

How long does it take to sell a home with a listing agent?

Time on market varies by price point, condition, and local demand across Stuart, Port St. Lucie, Jensen Beach, and the rest of the Treasure Coast. A listing agent's job is to shorten that timeline through accurate pricing from day one and consistent, daily marketing — rather than letting a home sit and grow stale on the MLS.


June 13, 2026

Riverland at Tradition – 55+ Active Adult Living in Port St. Lucie

Riverland at Tradition is one of Port St. Lucie's premier 55+ active adult destinations, spanning more than 4,000 beautifully landscaped acres in the heart of the Tradition area. Built by GL Homes, Riverland is conveniently located near Cleveland Clinic Tradition Hospital, I-95, and the shops, restaurants, and entertainment of Tradition Square.

Residents enjoy access to Riverland's resort-style shared amenities, including a 51,000-square-foot Wellness Center, Sports & Racquet Club, Arts & Culture Center, scenic Paseos for walking and biking, and dedicated green spaces and parks throughout the community.

Riverland at TraditionHomes for Sale

Homes for Sale in Riverland at Tradition

Whether you're searching for a move-in-ready resale home or a new construction floor plan from GL Homes, Riverland at Tradition delivers Florida's best 55+ lifestyle. Browse current listings below, or contact our team for a personal tour of the community.


May 30, 2026

Eric Slifkin: The Treasure Coast Real Estate Expert With a Forward-Looking Approach


Treasure Coast Real Estate

Why families across the Treasure Coast trust the Slifkin Team to find their next Florida home

Treasure Coast & Palm Beach, FL Keller Williams Realty 20+ years serving Florida
20+
Years on the Treasure Coast
$1M+
Many recent sales in this range
50
Units sold in one Hobe Sound project

When Eric Slifkin tells clients, "Need a new address? Start with ours!" — it isn't just a clever tagline. It's a promise backed by more than two decades of helping families relocate to Florida's Treasure Coast, a track record of high-end sales, and a technology-driven approach that was ahead of its time.

Who is Eric Slifkin?

Eric Slifkin, Broker Associate at Keller Williams Realty, Treasure Coast real estate expert
Eric Slifkin
Broker Associate · Keller Williams Realty · Founder, Slifkin Team

Florida real estate since 2002 · Serving the Treasure Coast & Palm Beach corridors

Eric Slifkin is a Broker Associate at Keller Williams Realty and the founder of the Slifkin Team, established in 2012. He specializes in residential real estate across the Treasure Coast corridor — including Stuart, Palm City, Hobe Sound, and Palm Beach — and holds multiple elite industry designations:

Certified Residential Specialist (CRS) Certified Luxury Home Specialist (CLHMS) Senior Real Estate Specialist (SRES®)

Originally from New Jersey, Slifkin relocated to Florida in 2002 — and quickly turned firsthand relocation experience into a career helping others do the same. Today, his team of listing specialists and buyers' agents focuses on one mission: simplify the buying or selling process while securing the best possible price, terms, and conditions for every client.

Recent highlights: what the Slifkin Team has accomplished

Results speak louder than credentials. Recent standout transactions include:

  • Selling out a 50-unit townhouse project in Hobe Sound
  • Virtually closing a $2,000,000 condo at the newly built Riverhouse in downtown Stuart
  • Selling a $4,000,000 waterfront property to a Florida-bound buyer — a lead that came directly through their website

These aren't isolated wins. They reflect a team that consistently performs across price points and property types, from starter homes to luxury waterfront estates.

Tech and digital marketing: ahead of the curve since day one

Long before digital real estate became the norm, Eric Slifkin was building lead-capture systems and client management tools from scratch — drawn from his background in information technology.

In 2003, when most agents were still relying on print ads and yard signs, Slifkin was engineering software solutions to capture online leads and track them efficiently. That technical instinct proved a significant competitive advantage as the market shifted online — and it continues to drive the way the Slifkin Team markets properties today.

Navigating market cycles: resilience built over 20 years

Slifkin has witnessed both the market crash of the 1990s and the great real estate recession of the late 2000s. His approach? Disciplined financial management and diversification. During the downturn, the team leaned heavily into the rental market to maintain cash flow — a strategy that kept the business healthy and positioned them to capture listings as conditions improved.

That kind of long-term thinking has defined the team's growth. Every year since launch has outperformed the one before.

The team advantage: why a team beats a solo agent

Slifkin is candid about the team model: it isn't for everyone. But for clients, it delivers real benefits:

Always available

A team member is always on call — no single point of failure, even in emergencies.

Deep expertise

Every team member draws on Slifkin's 20+ years of problem-solving and market experience.

Back-office excellence

Barbara Slifkin manages transaction details with precision praised by brokers, title companies, and lenders.

Serving buyers and sellers over 50: the SRES® difference

As a Senior Real Estate Specialist (SRES®), Eric Slifkin is specially trained to guide clients aged 50 and older — and their families — through major housing transitions. Whether downsizing, relocating closer to family, or moving into an active adult community, the Slifkin Team understands the financial and lifestyle considerations unique to this stage of life.

Why the Treasure Coast?

The Slifkins don't just sell this area — they live it. Their Palm City home, purchased over 20 years ago, sits in what Eric calls "rural-suburban" Florida: peaceful and spacious, yet close to shopping, top-rated schools, and medical facilities. That authentic connection to the community is felt in every client interaction.

The Treasure Coast continues to attract buyers seeking a less congested alternative to South Florida, with waterfront access, strong schools, and a lower cost of living than Miami or Fort Lauderdale.

Areas we serve

Stuart, FL
Palm City, FL
Hobe Sound, FL
Jensen Beach, FL
Port St. Lucie, FL
Palm Beach County

Frequently asked questions

The team serves the Treasure Coast and Palm Beach real estate corridors, including Stuart, Palm City, Hobe Sound, Jensen Beach, Port St. Lucie, and surrounding communities.
Yes. Eric Slifkin holds the Certified Luxury Home Marketing Specialist (CLHMS) designation, and many of the team's recent sales have been in the $1 million-plus range.
Three things: 20+ years of local market knowledge, a technology-driven marketing approach built from an IT background, and a tight-knit team structure that ensures every client gets consistent attention and detailed transaction management.
Yes. The Slifkin Team offers free, no-obligation consultations for buyers and sellers. It's an opportunity to discuss your goals with no pressure to commit.

Ready to buy or sell on the Treasure Coast?

Schedule your free, no-obligation consultation with Eric Slifkin and the team. Whether you're relocating to Florida or preparing to list, we'll help you navigate every step.

Book a free consultation →


No pressure. No obligation. Just honest guidance.